


Dear Investors,
In today’s edition of “Macro Mistakes,” we explore the Chinese Stock Market Crash of 2015, a dramatic event driven by speculative trading and the Chinese government’s efforts to stabilize an overheated market.
This episode serves as a key lesson on the risks of speculative trading, policy missteps, and the dangers of relying on government intervention to prop up markets.
The Story
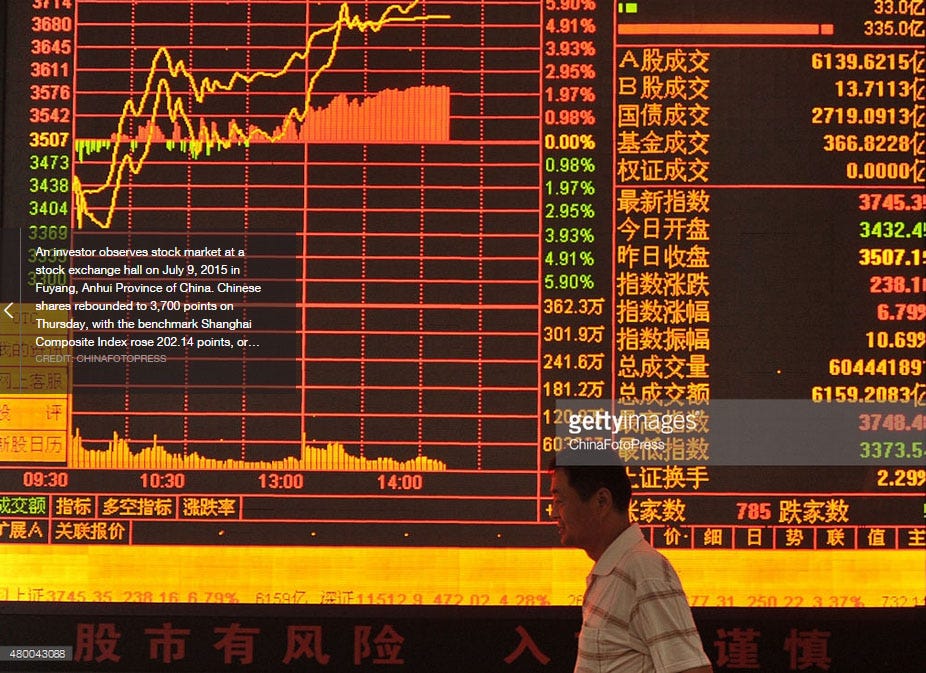
The early 2010s were a period of rapid growth for China’s stock markets.
Retail investors, many of whom had little experience or understanding of the risks involved, poured money into Chinese A-shares, fueling a speculative frenzy.
Encouraged by government rhetoric about the benefits of stock market participation, investors drove the Shanghai Composite Index up by nearly 150% in just one year, from mid-2014 to mid-2015.
Much of this growth was driven by margin trading, where investors borrowed money to buy stocks, significantly amplifying both gains and losses.
By June 2015, the Chinese stock market had reached unsustainable levels, with many stocks trading at extreme valuations.
Fearing a bubble, the China Securities Regulatory Commission (CSRC) began tightening margin requirements and implementing measures to curb speculative trading.
This triggered panic selling, as overleveraged investors were forced to liquidate their positions to cover their losses.
Within weeks, the Shanghai Composite Index plunged by over 30%, wiping out $3 trillion in market value.
In response, the Chinese government implemented unprecedented measures to stabilize the market, including halting trading on thousands of stocks, banning large shareholders from selling their shares, and encouraging state-owned enterprises to buy stocks.
However, these interventions did little to calm investor nerves, and the market remained volatile for months.
The Macro Mistake
The Chinese Stock Market Crash of 2015 was driven by several key macroeconomic mistakes, including excessive speculation and poor policy responses:
- Speculative trading and margin debt: The use of margin debt to fuel stock purchases created a highly leveraged market. When prices started to fall, margin calls forced investors to sell, exacerbating the decline.
- Overreliance on government intervention: Investors had grown accustomed to the idea that the Chinese government would step in to prevent market declines. However, the government’s interventions were ineffective and only prolonged the market’s volatility.
- Policy missteps: The government’s efforts to curb speculation by tightening margin requirements came too late and were too abrupt, triggering a sharp market correction. At the same time, the government’s intervention to prop up the market undermined confidence and fueled further uncertainty.
The Macro Lesson
The Chinese Stock Market Crash of 2015 provides several important macroeconomic lessons:
- Leverage amplifies risk: The widespread use of margin debt in China’s stock market magnified both gains and losses. When the market turned, leveraged investors were forced to sell, leading to a sharp and rapid decline in stock prices.
- Speculative trading is dangerous: Markets driven by speculative trading, rather than fundamentals, are prone to sharp corrections. Investors who chase quick profits without understanding the underlying risks can find themselves caught in sudden market downturns.
- Government intervention has limits: While government intervention can stabilize markets in the short term, it cannot prevent the underlying risks from playing out. Overreliance on government support can create complacency among investors and distort market signals.
The Chinese Stock Market Crash caused significant financial losses for millions of retail investors, many of whom had borrowed heavily to buy stocks.
The crash also exposed weaknesses in China’s regulatory framework and raised concerns about the stability of the country’s financial system.
In the wake of the crash, the Chinese government took steps to improve market regulation, including tighter controls on margin trading and increased scrutiny of financial products.
However, the crash highlighted the challenges of managing a rapidly growing and increasingly complex financial market.
Macro Bonus
Investors who recognized the speculative nature of China’s stock market and reduced their exposure before the crash were able to avoid significant losses.
Additionally, those who understood the risks of margin trading and the potential for a government intervention failure were better positioned to navigate the market volatility.
The lessons from the Chinese Stock Market Crash are still relevant, particularly in markets where speculative trading and leverage are prevalent.
The Chinese Stock Market Crash of 2015 serves as a reminder of the dangers of speculative trading, excessive leverage, and the limits of government intervention.
Next time, we’ll explore another macro mistake and how its lessons can help us better navigate the ever-changing landscape of global markets.
Market analyses you can’t miss
- Why This Macro Rally Could End in a Disaster
- Trump’s $3 Trillion Trade Shock
- Disaster is arrived