Cross-asset strategy · Monthly
Institutional
Macro Report October 2026
A hawkish hold, a 10-year that broke from oil and credit cracking under record earnings, a consolidated read of the month through the lens of price.
Reserved research
Institutional seats only, never published, never indexed
Cross-asset strategy · Monthly
A hawkish hold, a 10-year that broke from oil and credit cracking under record earnings, a consolidated read of the month through the lens of price.
What every edition covers
The structure doesn't move, which is the point: an investment team can compare one month against the last without relearning the document. Each ring shows how many of the 24 exhibits sit in that part.
Policy, rates and the real economy. The FOMC statement, the hike odds, inflation against neutral and the 10-year against oil.
8 exhibitsEarnings, valuation and the return outlook. EPS against the P/E, the PEG, bonds against equities and drawdowns by Fed cycle.
6 exhibitsPositioning, ownership and market structure. High yield spreads, the bubble watch, excess liquidity and tokenized equity.
5 exhibitsThe dollar, hard assets and the debasement thesis. Equity inflows and the deficit, gold exports, gold and commodities.
5 exhibitsWhat it does for your firm
The report isn't the product. The product is the hours it gives back and the argument it lets you defend in front of a client 6 months later.
An analyst on the payroll costs a salary and takes months to onboard. This starts the same day, and the cadence never depends on whether that person is on holiday.
Bulge bracket notes arrive with a licence you can't pass on and a whole department behind every word. Here there's 1 name attached, and it stays attached when the call is wrong.
Every adviser reads the same evidence in the same structure, so the firm stops saying 4 different things to 4 different clients in the same week.
A sample of the thinking
Not a teaser. The actual argument that ran through 24 exhibits that month, compressed to what an investment team needs to hear first. The bullish and the cautious readings are in sequence, not in conflict.
October's hold at 3.75%-4.00% passed 10-2, with two dissents for a hike, and the promise of a "timelier" return to 2% was removed. Core PCE is back at 3.1% and policy sits about 60 basis points above neutral.
The 10-year closed September at 5.30%, its highest since April 2002, and kept rising on days oil fell, the signature of a buyer problem rather than an inflation one. Net interest absorbs about 14 cents of every federal dollar.
Trailing EPS is up 33% and the P/E is down 16%, so the entire +12% of the year came from profits. The 10-year yields 1.47 points more than the S&P 500 earnings yield, the widest gap since 2002.
CCC spreads reached 12.0%, the widest since November 2022, with the S&P 500 at its highs, and every spike above 11% came with a drawdown of at least 14%. The G10 excess liquidity gauge fell to about -0.8.
About 100% of the current account deficit is funded by foreign equity buying, with the top ten at 40% of the index, so a tech correction can now weaken the dollar. Central banks bought gold for a fifth month.
The November refunding leans on bills and the 10-year falls back below 5%, as after 1 November 2023. The dollar weakens and the midterm low carries the index toward 9,000-9,150 by mid-2027.
The 10-year breaks 5.30% toward 5.50%-5.75% and CCC spreads take out the 12.9% of 2022. The multiple takes a 2018-style hit toward 7,000-7,200.
Every call is dated and archived, including the ones that aged badly.
Coverage
Nothing is dropped when it gets boring and nothing is added because it's in the news. The same 13 series, on the same definitions, so one month can be compared against the last.
Sentiment & dollar
Equities & growth
Inflation & commodities
Real estate & income
Both sides, on every market, every week. A view without its counter argument is a marketing line.
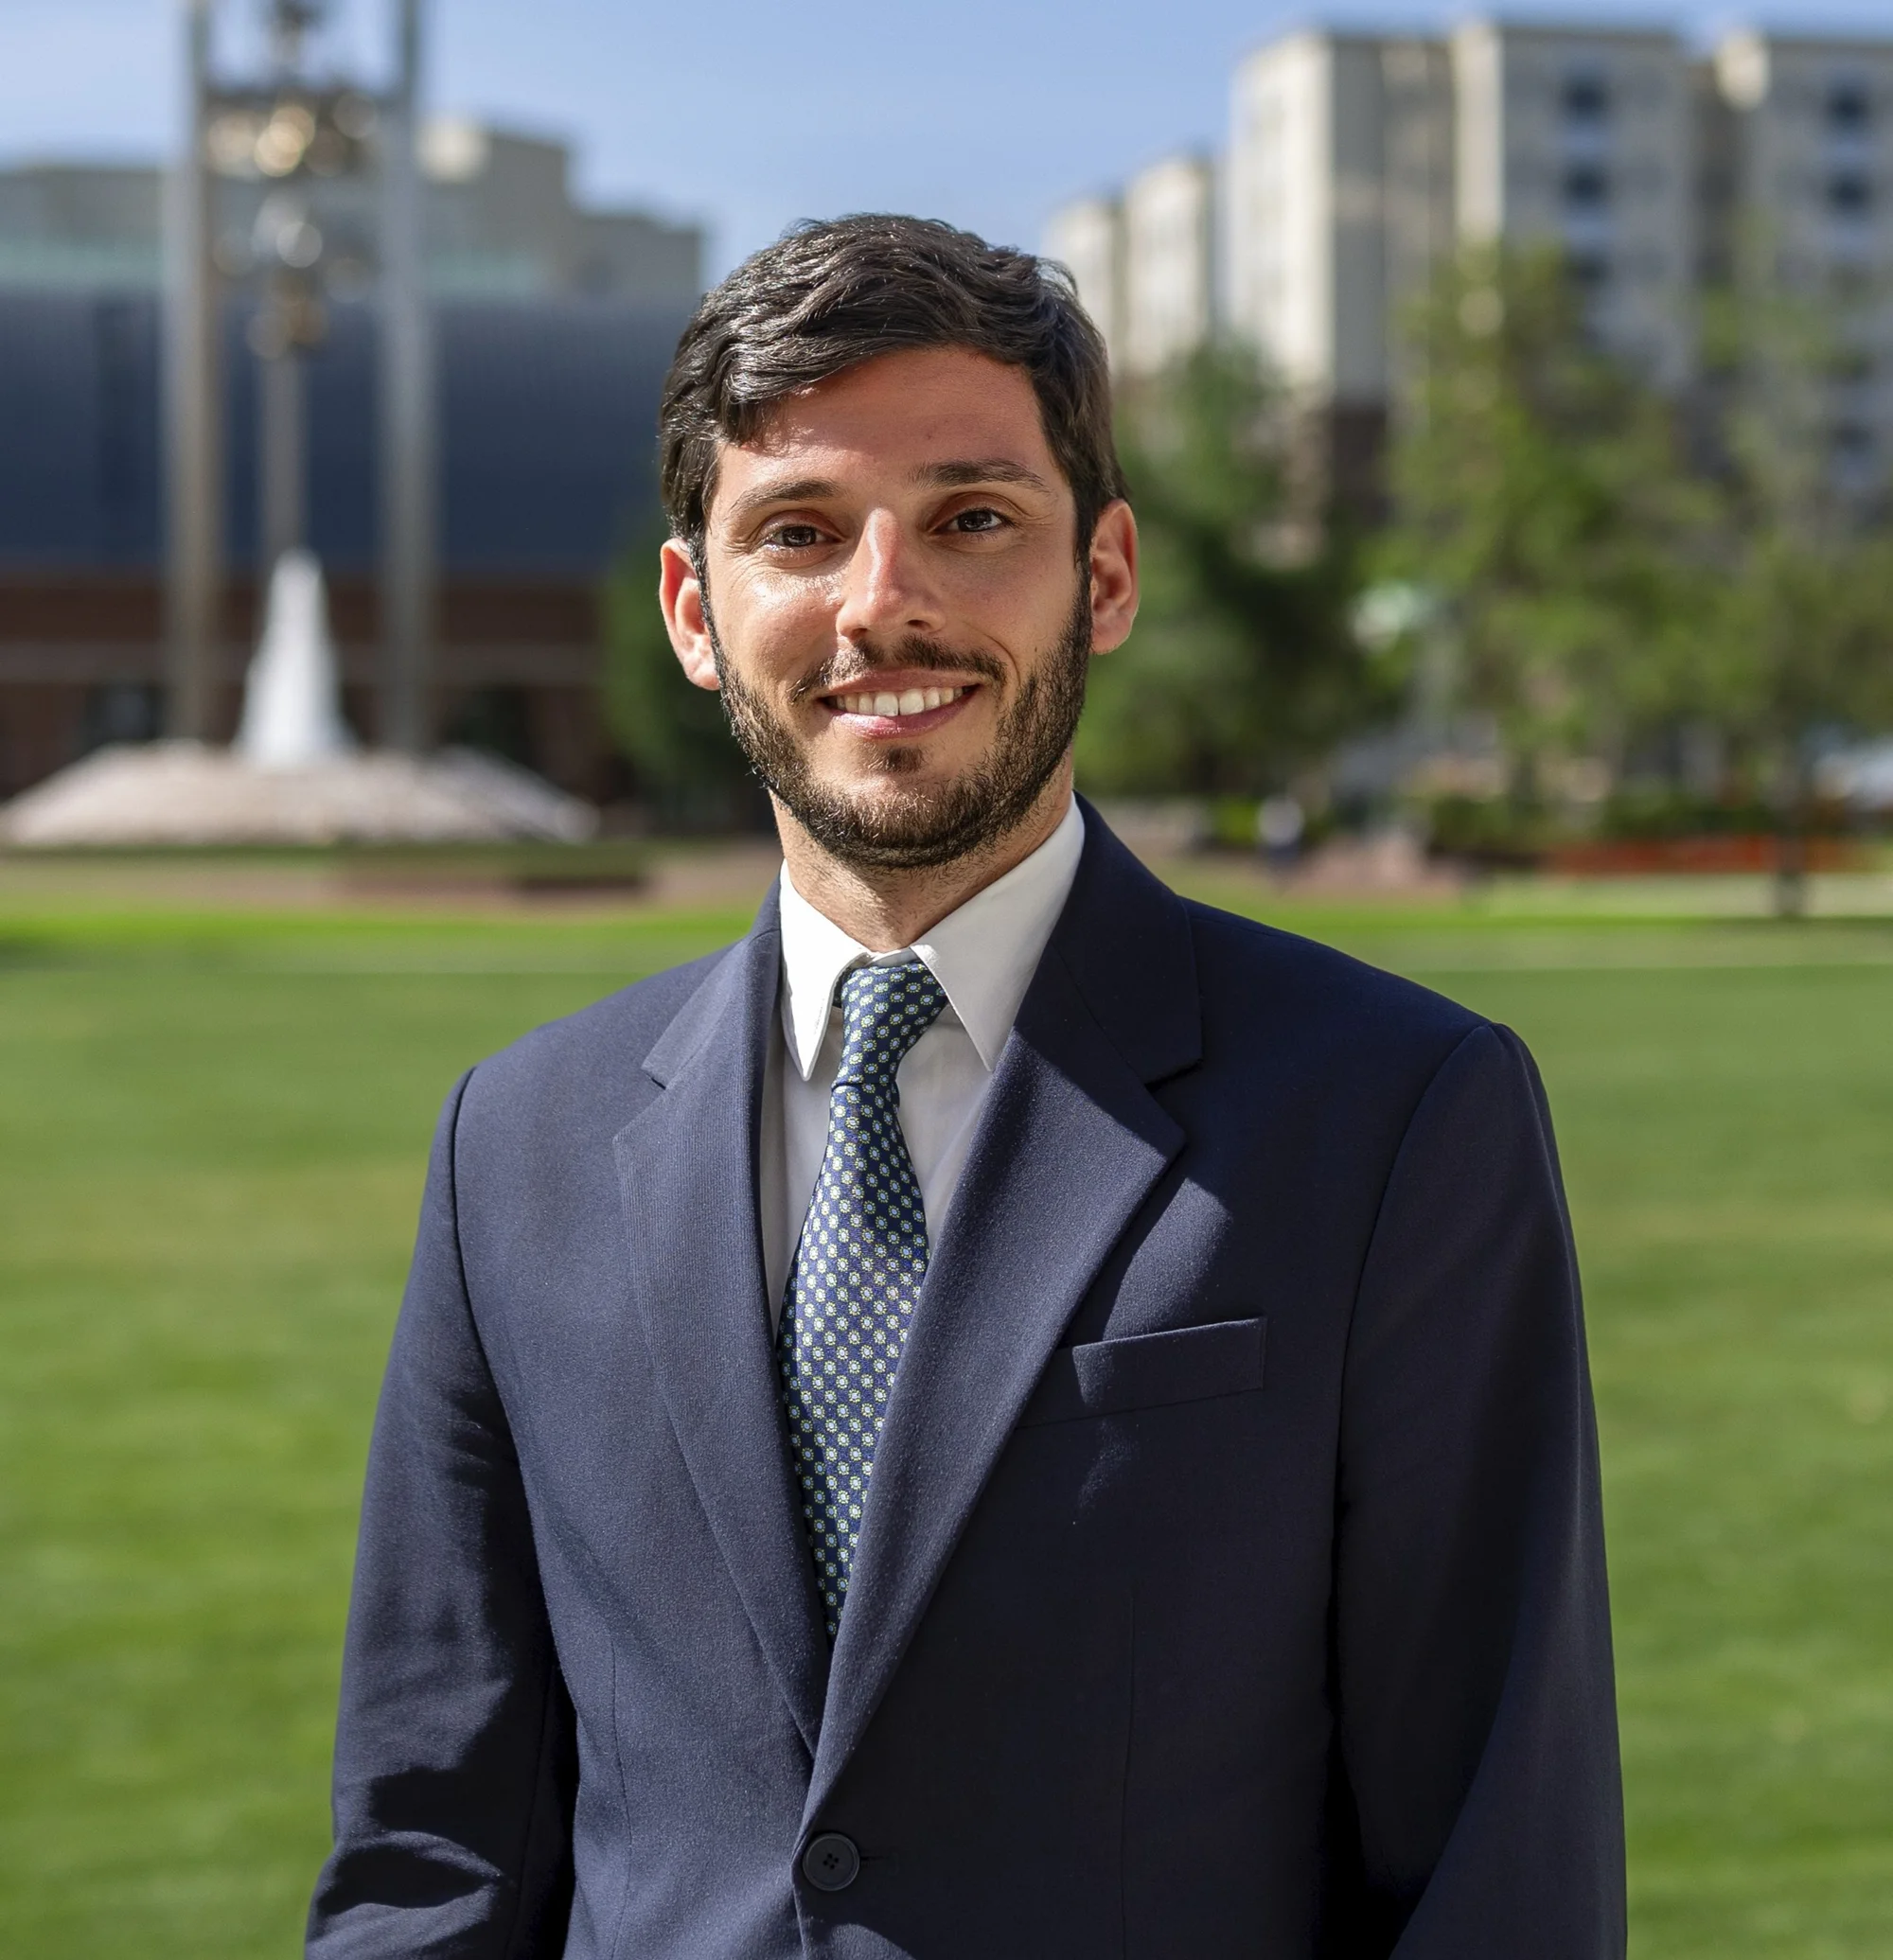
Alessandro, founder and head of research
And the analyst behind it
The person who builds the model is the person who answers the email. No research department to hide behind, and no account manager in between. That's the whole reason the cohort stays small.
A standing strategy call. Your positioning, your questions, on the record.
Not a ticket queue. Urgent requests come straight to the analyst's inbox.
On request, the month's evidence reframed for your investment team.
Walked through, not just sent
A team briefing isn't a PDF read aloud. It's the same evidence taken apart on a call, with the counter argument put on the table before you have to ask for it.
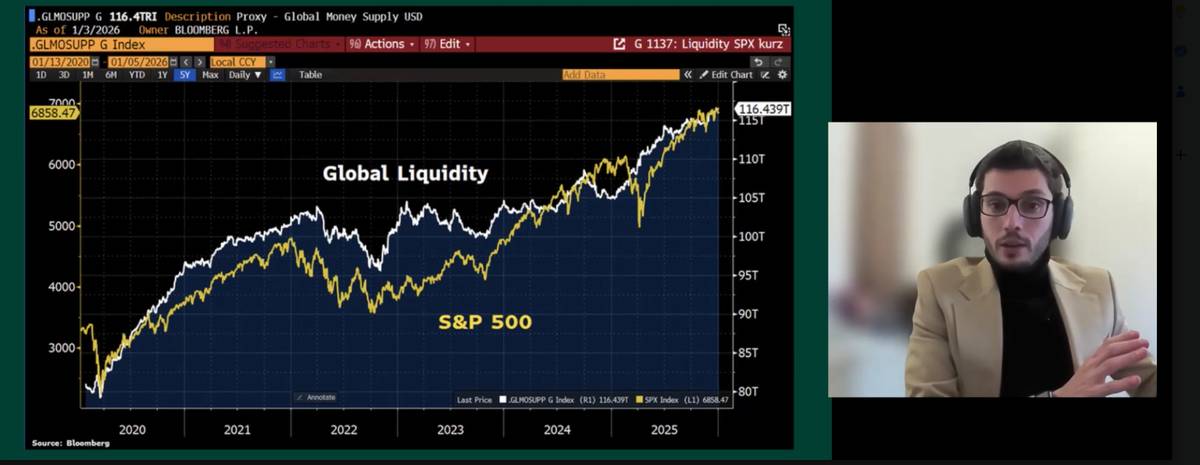
Private - The Committee Room
I take one of the most useful questions from The Inner Circle, raise it to the level of an investment committee and answer it in depth from the Institutional report, with its exhibits. Anonymous, always.
What's your view on the dollar and the AI bubble?
How should an investment committee interpret the dollar's breakout to a 19-month high alongside stretched valuations in AI-related technology sectors, particularly when semiconductor multiples echo the levels seen at the internet peak in 2000, and what mechanism links currency strength to both valuation compression and broader market stress?
The briefing opens inside the dashboard.
Never the same shape twice
Who reads the briefings.
Read every question the members are asking, and tell me yours when you join. The best enter The Inner Circle, anonymously.
The Inner Circle in full, filed by market. And your first Committee Room briefing, on me.
The whole Committee Room, with the exhibits from the Institutional report.
Free to open, just your email. Becoming a PRO member of the dashboard is one click away inside.
Request access
Tell us what you are working on across the 13 markets. Every request is read at Macro Mornings, and the reply covers what exists, what we can build, and how long it takes.
Firms and individual investors are both welcome. If the question falls outside what we cover, we will say so.
Request received
A confirmation is on its way to your inbox, and you will be contacted as soon as possible. If anything is missing, reply to that email and it reaches us directly.