


Dear Investors,
-
Introduction
Rethinking Diversification: It’s Not What You Think
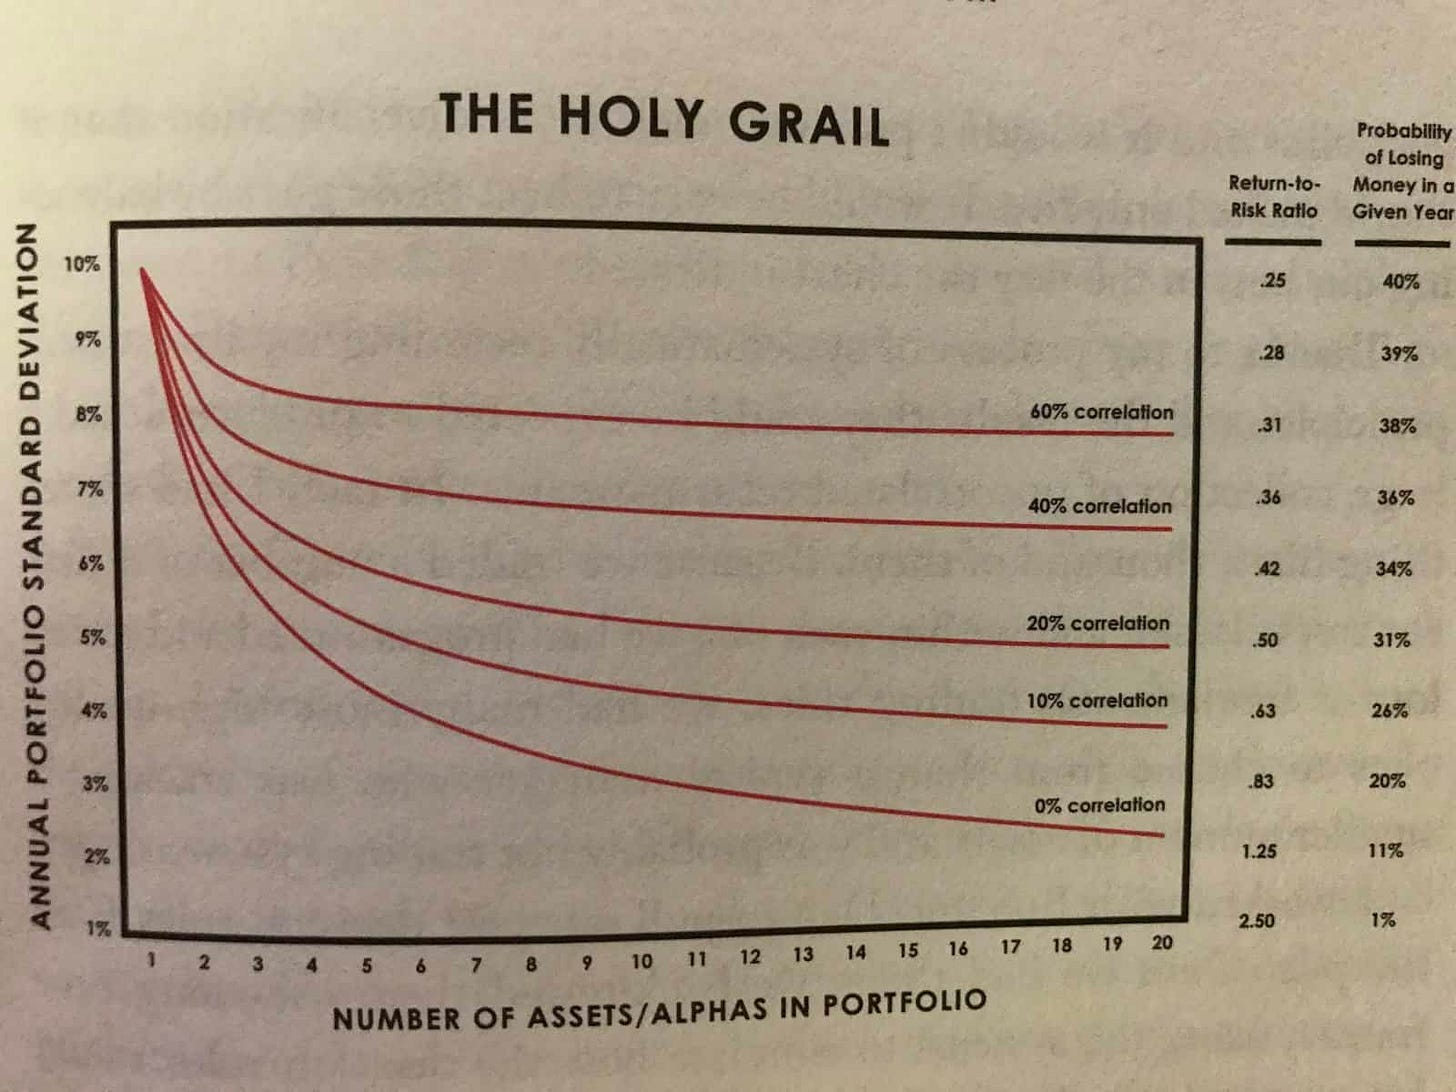
For years, I thought I understood diversification. Own some stocks, some bonds, maybe a bit of gold, and call it a day. But I was wrong – and I didn’t realize how wrong until I read Ray Dalio’s early writings on portfolio construction. Dalio makes a critical distinction: diversification is not about owning many things – it’s about owning uncorrelated things. That small shift in thinking changes everything. In Dalio’s words, if you can find 15 to 20 good, uncorrelated return streams, you can reduce your portfolio risk by 80% without sacrificing expected return. Let me repeat that: an 80% risk reduction, not by hedging, not by cutting exposure – but by combining assets that move differently. Most investors don’t do this. They think they’re diversified because they hold a mix of equities from the U.S., Europe, and emerging markets. But when crises hit – like in 2008 or 2020 – those assets tend to move in the same direction. Why? Because their underlying drivers are correlated: global growth, risk sentiment, liquidity flows. Real diversification begins when you break free from that pattern.
Bridgewater’s Formula: Correlation Over Quantity
Bridgewater built its All Weather portfolio using this exact philosophy. Rather than betting on which asset will perform best, the portfolio is designed to perform reasonably well in any economic environment – growth rising or falling, inflation rising or falling. That creates four macro “seasons,” and the goal is to own asset classes that thrive in each one. Here’s where the math gets powerful. Dalio and his team quantified that the volatility of a portfolio is not the average volatility of the assets – it’s determined largely by how correlated those assets are. If you hold two assets each with 10% volatility, but they’re perfectly correlated, your portfolio still has 10% volatility. But if they’re uncorrelated, that number drops to around 7%. Add a third, uncorrelated stream and it drops even further. This isn’t theory – it’s practice. During the 2008 crisis, while most traditional 60/40 portfolios dropped over 30%, Bridgewater’s Pure Alpha strategy was up 9%. Why? Because they weren’t just diversified – they were anti-correlated in key areas, especially with assets like nominal bonds and commodity-linked positions that moved inversely to risk assets. And that’s where most investors fall short. They optimize for return, but ignore the structure of their risk. It’s like building a house with beautiful furniture but a shaky foundation. When the storm comes, aesthetics won’t save you.
How I Rewired My Portfolio Thinking
The first time I applied this concept, I was skeptical. I was used to overweighting the highest-conviction ideas – U.S. tech stocks, for example – and sprinkling in a few “hedges.” But then I started asking: How do these assets behave when inflation surprises? What happens when real yields spike? What if growth collapses but central banks hesitate to cut? I realized I wasn’t diversified – I was simply exposed to the same economic narrative in slightly different packaging. So I started building exposure based on macro regimes, not sectors or countries. I combined assets that historically perform well in different environments: inflation-linked bonds for stagflation, equities for disinflationary booms, commodities for unexpected price shocks, and cash as an option on volatility. I also analyzed correlations not just in normal times – but during stress events. The result? My portfolio became less fragile. In 2022, when inflation spiked and both stocks and bonds sold off, I was better positioned. I wasn’t trying to predict the next move – I was trying to survive all moves. That’s Dalio’s Holy Grail. Not a magic formula, but a mindset: seek resilience, not brilliance.
What This All Means
Diversification is often misunderstood as a box-ticking exercise. But Dalio’s version of it – true diversification – requires intellectual rigor. It asks you to think probabilistically, not just optimistically. It challenges you to measure how things behave together, not just in isolation. If you want to think like a macro strategist, you need to move beyond returns and toward interactions. What matters is not just what you own, but how those pieces move when the world shifts beneath your feet. So stop asking “How much return will this asset give me?” and start asking “What role does this play in the bigger system?” Next week, we’ll explore one of the most fascinating thinkers in macro history – George Soros – and how his concept of reflexivity turned perception into profit.
Market analyses you can’t miss
Why This Macro Rally Could End in a Disaster 2. Trump’s $3 Trillion Trade Shock 3. Disaster is arrived