


Dear Investors,
In today’s edition of “Macro Mistakes,” we dive into the Latin American Debt Crisis of the 1980s, a period when many countries in the region, particularly Mexico, Brazil, and Argentina, fell into severe economic hardship due to excessive borrowing.
This crisis teaches us crucial lessons about sovereign debt management, external shocks, and the long-term consequences of ignoring macroeconomic fundamentals.
The Story
In the 1970s, Latin American economies were booming, and many governments borrowed heavily from international lenders to finance development projects, infrastructure, and industrialization.
These loans were often denominated in U.S. dollars, making the countries vulnerable to changes in global interest rates and currency fluctuations.
By the early 1980s, the global economic landscape had changed dramatically.
The U.S. Federal Reserve, under Paul Volcker, raised interest rates sharply to combat inflation.
This increase in global interest rates made it much more expensive for Latin American countries to service their foreign-denominated debt.
At the same time, global commodity prices, a key source of revenue for many Latin American countries, were declining, exacerbating their fiscal challenges.
In August 1982, Mexico announced that it could no longer meet its debt obligations, setting off a chain reaction of defaults across the region.
Countries like Brazil and Argentina followed suit, unable to service their massive debts.
This crisis plunged Latin America into a decade of economic stagnation, often referred to as the “Lost Decade.”
The Macro Mistake
The Latin American Debt Crisis was driven by several key macroeconomic mistakes, most notably overborrowing and exposure to external shocks:
- Excessive sovereign debt: Many Latin American countries borrowed far beyond their ability to repay, assuming that global economic conditions would remain favorable indefinitely. When interest rates rose, these countries were unable to meet their debt obligations.
- Currency mismatches: Borrowing in foreign currencies while generating revenues in local currencies created significant risk. When local currencies depreciated, the cost of servicing U.S. dollar-denominated debt soared, leading to widespread defaults.
- Failure to build reserves: Despite borrowing heavily, many Latin American countries failed to build sufficient foreign reserves to cushion against external shocks like rising interest rates or falling commodity prices.
The Macro Lesson
The Latin American Debt Crisis provides several important macroeconomic lessons:
- Sovereign debt must be managed carefully: Countries should avoid accumulating unsustainable levels of debt, particularly when borrowing in foreign currencies. Sound debt management practices are essential to maintaining economic stability.
- External shocks matter: Global interest rates and commodity prices can have a profound impact on emerging markets. Countries that rely heavily on commodity exports or foreign borrowing must be prepared for external shocks and build reserves accordingly.
- Currency mismatches are dangerous: Borrowing in foreign currencies while earning revenues in local currencies creates a significant risk. When exchange rates shift, the cost of repaying foreign-denominated debt can become unsustainable.
The Latin American Debt Crisis led to a decade of economic stagnation across the region.
Countries like Mexico, Brazil, and Argentina faced severe recessions, high inflation, and rising unemployment.
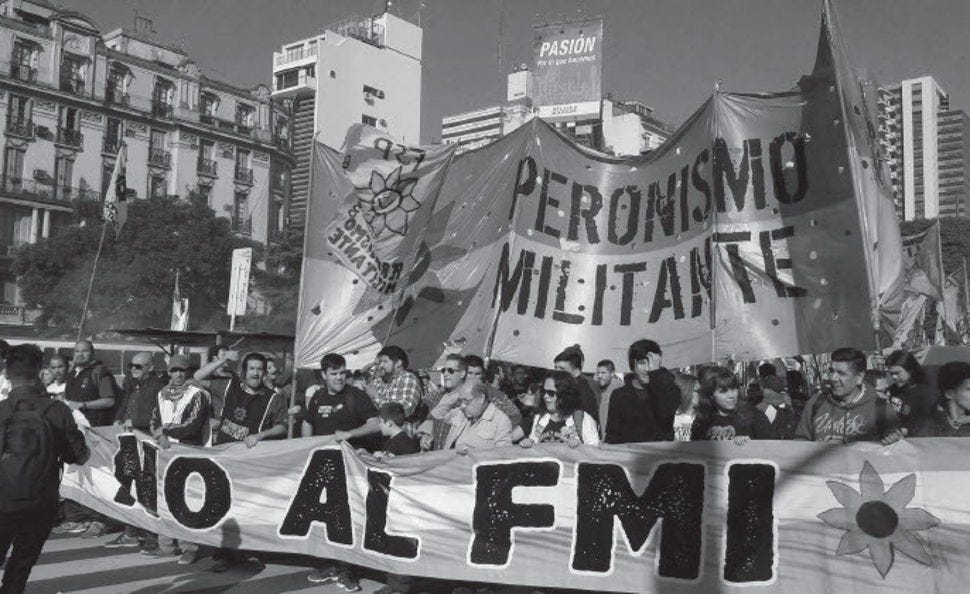
The crisis also led to widespread social unrest and political instability, as governments implemented austerity measures to meet the conditions of International Monetary Fund (IMF) bailout programs.
In , many Latin American countries were forced to restructure their debts, privatize state-owned enterprises, and implement painful economic reforms.
While these reforms eventually helped stabilize the region’s economies, the social costs were significant, and the recovery was slow.
Macro Bonus
Investors who recognized the risks of overborrowing and currency mismatches in Latin America were able to avoid significant losses by reducing their exposure to the region before the crisis hit.
Additionally, those who understood the broader macroeconomic risks – such as rising global interest rates – were better positioned to navigate the fallout from the debt crisis.
The lessons from the Latin American Debt Crisis are still relevant for emerging markets that rely heavily on foreign borrowing or are vulnerable to external shocks.
The Latin American Debt Crisis serves as a reminder of the dangers of overborrowing, currency mismatches, and the importance of preparing for external shocks.
Next time, we’ll explore another macro mistake: The Russian Financial Crisis (1998) and how sovereign default sent shockwaves through global markets.