


Dear Investors,
In this edition of “Macro Mistakes,” we examine the Russian Financial Crisis of 1998, a dramatic event that led to a sovereign debt default and the sharp devaluation of the ruble.
This crisis underscores the dangers of overborrowing, currency mismatches, and the risks that come with political and economic instability in emerging markets.
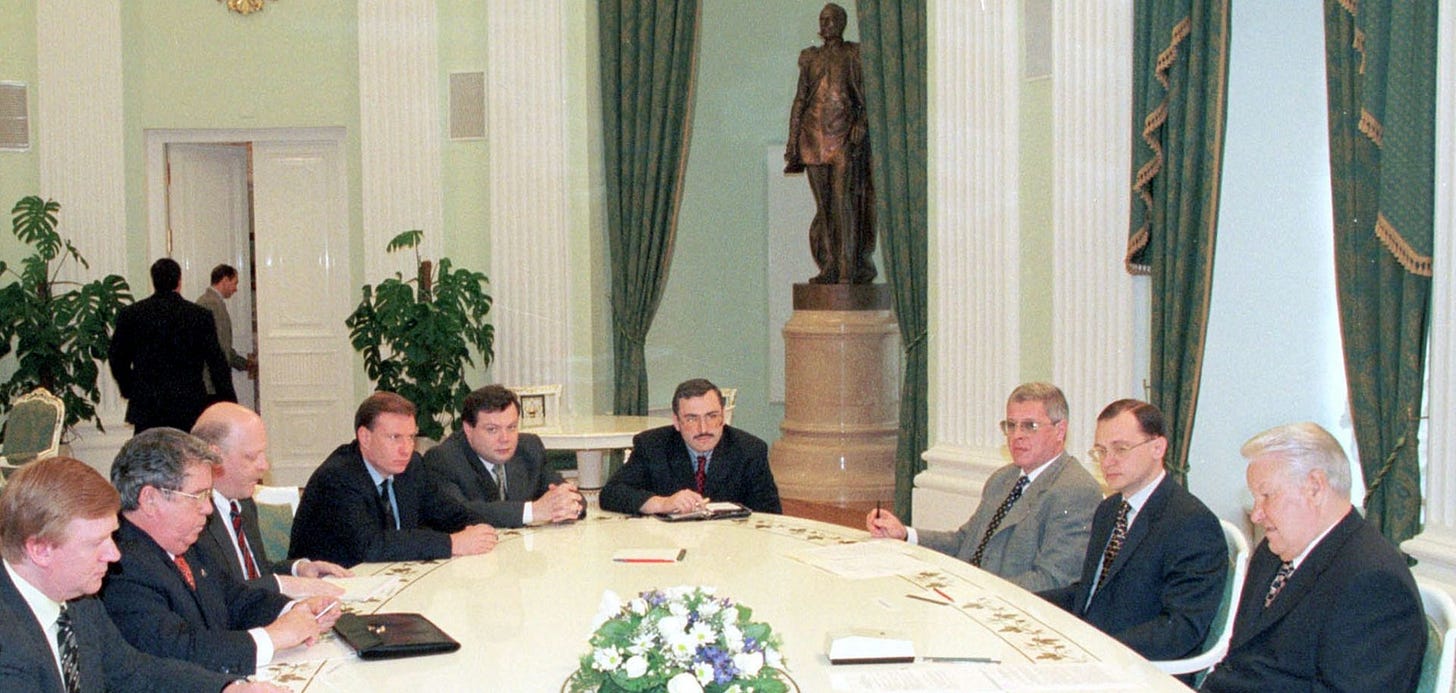
The Story
In the early 1990s, following the collapse of the Soviet Union, Russia was transitioning from a centrally planned economy to a market-based system.
During this period of rapid transformation, the Russian government borrowed heavily from international lenders, issuing substantial amounts of foreign-currency-denominated debt to finance its fiscal deficits.
However, Russia’s economic reforms were insufficient to stabilize its economy.
By the late 1990s, the country was grappling with high inflation, political instability, and an economy heavily dependent on oil exports.
When global oil prices plummeted in 1997, Russia’s fiscal revenues collapsed, and the government was left struggling to meet its debt obligations.
By August 1998, Russia’s foreign reserves were nearly depleted, and the government announced that it would default on $40 billion of its domestic debt and allow the ruble to float freely, abandoning its defense of the currency.
The ruble depreciated by more than 70%, sending shockwaves through global financial markets and triggering widespread panic among investors.
The Macro Mistake
The Russian Financial Crisis was the result of several critical macroeconomic mistakes, including sovereign debt mismanagement and currency mismatches:
- Overborrowing in foreign currency: Russia’s heavy reliance on foreign-currency debt left the country vulnerable to external shocks. When oil prices collapsed, the government’s ability to service its debt in foreign currency evaporated, leading to default.
- Currency mismatches: Russia borrowed in U.S. dollars while generating revenues in rubles, creating a significant currency mismatch. When the ruble devalued, the cost of servicing dollar-denominated debt soared, pushing the country into default.
- Failure to diversify the economy: Russia’s economy was overly reliant on oil exports, making it vulnerable to fluctuations in global commodity prices. The collapse of oil prices in 1997 played a major role in the country’s fiscal crisis.
The Macro Lesson
The Russian Financial Crisis offers several important macroeconomic lessons:
- Sovereign debt management is crucial: Countries that rely heavily on foreign borrowing, especially in foreign currencies, are vulnerable to external shocks. Proper debt management, including diversifying funding sources and building reserves, is essential to maintaining economic stability.
- Currency mismatches are risky: Borrowing in foreign currencies while generating revenues in local currencies creates a significant risk. When exchange rates shift, the cost of servicing foreign debt can become unsustainable.
- Economic diversification is key: Countries that rely heavily on one sector or commodity for revenue are at risk when global prices fluctuate. Diversifying the economy can help mitigate the impact of external shocks.
The Russian Financial Crisis led to a severe economic contraction in the country.
GDP shrank by 5% in 1998, inflation surged, and the country’s banking sector faced widespread collapse.
The ruble’s sharp depreciation wiped out the savings of millions of Russian citizens, leading to widespread social unrest.
The crisis also had global repercussions. International investors, who had exposure to Russian assets, were forced to liquidate positions, causing a wave of selling across emerging markets.
The collapse of Long-Term Capital Management (LTCM), a U.S. hedge fund with significant exposure to Russian debt, nearly triggered a global financial meltdown.
In of the crisis, Russia implemented a series of painful reforms to stabilize its economy, including restructuring its debt, stabilizing the ruble, and attracting foreign investment.
Over time, the country’s economy recovered, but the crisis left a lasting scar on its reputation in international financial markets.
Macro Bonus
Investors who recognized the risks of sovereign debt mismanagement and currency mismatches in Russia were able to reduce their exposure before the crisis hit.
Additionally, those who understood the potential for external shocks to trigger crises in emerging markets were better positioned to navigate the fallout.
The lessons from the Russian Financial Crisis are still relevant for emerging markets that rely heavily on foreign borrowing or are vulnerable to commodity price fluctuations.
The Russian Financial Crisis serves as a reminder of the dangers of sovereign debt mismanagement, currency mismatches, and the risks associated with over-reliance on a single commodity for economic stability.
Next time, we’ll explore another macro mistake: The Eurozone Debt Crisis (2010s) and how sovereign debt mismanagement nearly brought down the European Union.