


Dear Investors,
In today’s edition of “Macro Mistakes,” we explore the Japan Asset Bubble of the late 1980s and early 1990s, a period of excessive speculation in real estate and stocks that ultimately led to Japan’s Lost Decade of economic stagnation.
This event offers valuable lessons about speculative bubbles, monetary policy, and the long-term consequences of ignoring macroeconomic fundamentals.
The Story
During the 1980s, Japan’s economy was booming.
The country had become a global economic powerhouse, thanks to its dominance in industries like automobiles and electronics.
However, as Japan’s economy expanded, speculative behavior began to emerge in its financial markets, particularly in real estate and stocks.
Driven by loose monetary policies from the Bank of Japan (BOJ) and high levels of corporate and household borrowing, asset prices skyrocketed.
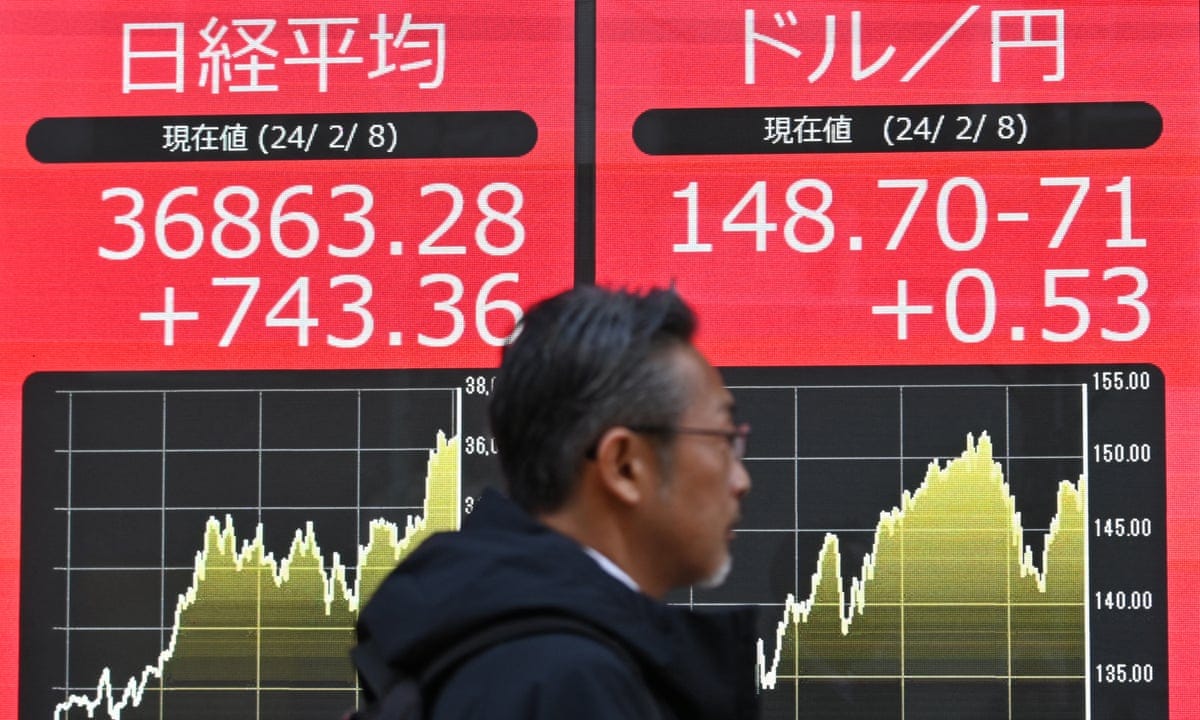
By 1989, Japan’s Nikkei 225 stock index had more than tripled in value, and the prices of real estate in major cities like Tokyo had reached unprecedented levels.
The total value of land in Japan was estimated to be worth more than the entire land value of the United States, despite Japan being a much smaller country.
However, this rapid rise in asset prices was not sustainable. In 1990, the BOJ raised interest rates to combat inflation and cool down the overheated economy.
This marked the end of Japan’s asset bubble.
The stock market crashed, with the Nikkei 225 losing nearly 60% of its value over the next two years.
Real estate prices followed suit, plunging by more than 80% in some areas.
The Macro Mistake
The Japan Asset Bubble was driven by several key macroeconomic mistakes, including excessive speculation and poor monetary policy management:
- Excessive speculation in assets: Investors became overly optimistic about the future of Japan’s economy and began speculating on real estate and stocks, driving asset prices far beyond their fundamental values.
- Loose monetary policy: The BOJ’s decision to keep interest rates low for an extended period contributed to the speculative frenzy. Cheap credit fueled excessive borrowing, which in turn inflated asset prices to unsustainable levels.
- Late intervention: When the BOJ finally acted to raise interest rates, it did so too late. By then, the bubble had grown so large that the resulting crash devastated the economy, leading to a prolonged period of deflation and economic stagnation.
The Macro Lesson
The Japan Asset Bubble provides several important macroeconomic lessons:
- Speculative bubbles are dangerous: When asset prices rise too quickly, detached from fundamental values, they become vulnerable to sharp corrections. Investors should be wary of markets where prices are driven by speculation rather than earnings or productivity growth.
- Monetary policy timing is critical: Central banks play a key role in managing economic growth. Maintaining low interest rates for too long can fuel asset bubbles, while raising rates too late can trigger a severe economic downturn. Central banks must strike a careful balance to prevent bubbles without stifling growth.
- Long-term consequences of bubbles: The collapse of Japan’s asset bubble had long-lasting effects. The country experienced more than a decade of stagnation, with deflation and slow economic growth. This serves as a reminder that the fallout from speculative bubbles can persist for many years.
The bursting of Japan’s asset bubble led to the Lost Decade, a period of prolonged economic stagnation that lasted throughout the 1990s and into the 2000s.
During this time, Japan experienced deflation, weak consumer demand, and low investment, as households and businesses were burdened by high levels of debt.
Real estate values never fully recovered, and Japan’s stock market remained well below its 1989 peak for decades.
The BOJ responded by lowering interest rates to near-zero levels and implementing quantitative easing in an attempt to stimulate the economy.
However, the damage caused by the asset bubble collapse was so severe that these policies had only limited success in reviving economic growth.
Macro Bonus
Investors who recognized the speculative nature of Japan’s asset bubble and reduced their exposure to real estate and stocks before the crash were able to avoid significant losses.
Additionally, those who understood the potential for a prolonged period of deflation and economic stagnation were better positioned to navigate the challenging investment environment that followed.
The lessons from the Japan Asset Bubble are still relevant, particularly in markets where asset prices have risen rapidly.
The Japan Asset Bubble serves as a powerful reminder of the dangers of speculative bubbles, loose monetary policy, and the long-term consequences of ignoring macroeconomic fundamentals.
Next time, we’ll explore another macro mistake: The Chinese Stock Market Crash of 2015 and how speculative trading led to a dramatic market collapse.
Market analyses you can’t miss
- Why This Macro Rally Could End in a Disaster
- Trump’s $3 Trillion Trade Shock
- Disaster is arrived