


Dear Investors,
In today’s edition of “Macro Mistakes,” we examine the Argentine Debt Crisis of 2001, a period of economic turmoil marked by the largest sovereign default in history.
This crisis provides valuable lessons about currency pegging, sovereign debt management, and the dangers of rigid economic policies in the face of external shocks.
The Story
In the 1990s, Argentina experienced a period of relative economic stability after years of hyperinflation and political unrest.
This stability was largely achieved through a currency peg, where the Argentine peso was fixed at a 1:1 exchange rate with the U.S. dollar.
The currency peg helped bring down inflation and attract foreign investment, but it also created significant challenges.
While the currency peg stabilized the economy in the short term, it limited Argentina’s ability to respond to external shocks.
The country’s ability to devalue its currency was effectively eliminated, which became a critical issue as the global economy shifted.
In the late 1990s, Brazil, Argentina’s largest trading partner, devalued its currency, making Argentine exports less competitive.
At the same time, Argentina had accumulated significant levels of sovereign debt, much of it denominated in U.S. dollars.
The strong peso made it difficult for the government to generate the necessary revenues to service this debt.
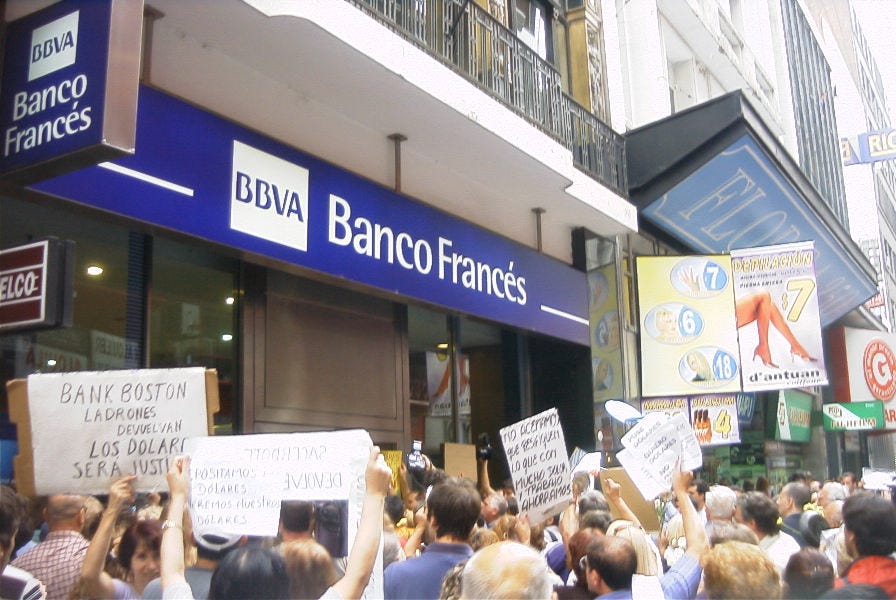
By 2001, the economy was in freefall, with unemployment exceeding 20%, the banking system in crisis, and the government struggling to meet its debt obligations.
In December 2001, Argentina defaulted on $93 billion of sovereign debt, marking the largest sovereign default in history.
The government was forced to abandon the currency peg, leading to a sharp devaluation of the peso.
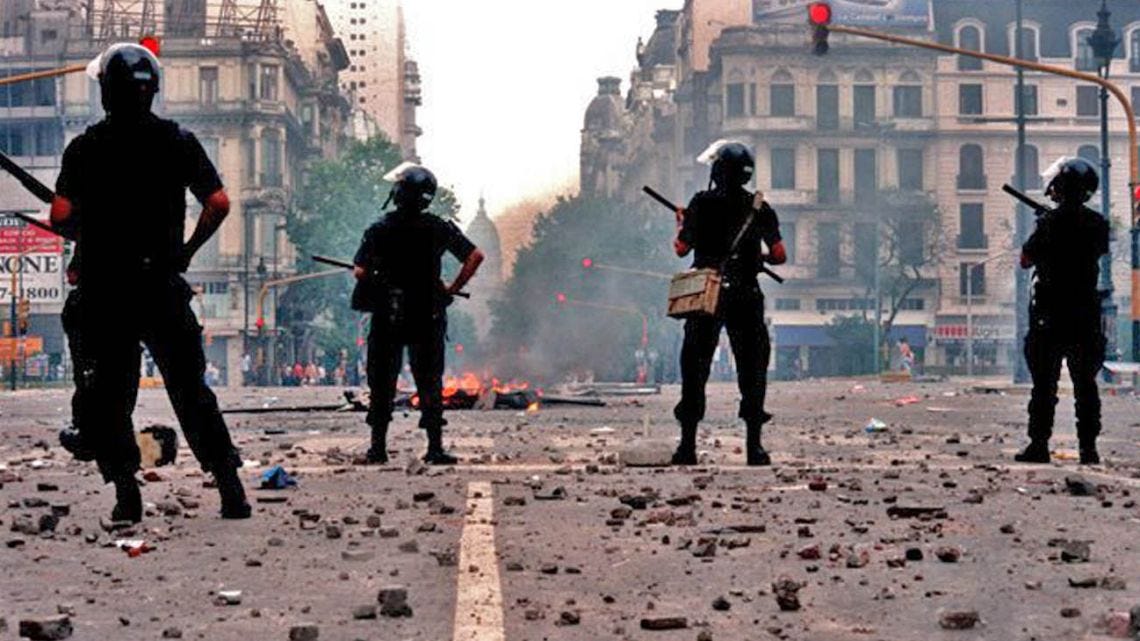
The economic collapse triggered widespread social unrest, with protests, bank runs, and the resignation of multiple Argentine presidents in rapid succession.
The Macro Mistake
The Argentine Debt Crisis was driven by several key macroeconomic mistakes:
- Currency pegging: Argentina’s decision to peg the peso to the U.S. dollar created a rigid economic system that couldn’t adapt to changing global conditions. The currency peg made it impossible for Argentina to devalue its currency to regain competitiveness.
- Overborrowing in foreign currency: Much of Argentina’s sovereign debt was denominated in U.S. dollars, creating a currency mismatch. As the peso remained overvalued, it became increasingly difficult for the government to service its dollar-denominated debt.
- Failure to adjust policies: Despite growing economic pressures, Argentina’s policymakers were reluctant to abandon the currency peg or implement fiscal reforms. This inflexibility exacerbated the crisis, leading to a full-blown economic collapse.
The Macro Lesson
The Argentine Debt Crisis offers several important macroeconomic lessons:
- Currency pegs are risky: While currency pegs can provide short-term stability, they also create rigidities that can make it difficult for economies to adjust to external shocks. Countries that rely on currency pegs must be prepared for the potential consequences of abandoning them when necessary.
- Debt management is crucial: Borrowing in foreign currencies can expose countries to significant risks, particularly when their domestic economy is not aligned with global economic trends. Sovereign debt must be carefully managed to avoid currency mismatches and unsustainable debt levels.
- Flexibility in policy is key: Governments must remain flexible in their economic policies to adapt to changing conditions. Sticking to rigid policies, such as currency pegs or unsustainable fiscal practices, can exacerbate crises and lead to worse outcomes.
The peso’s sharp devaluation led to a collapse in living standards, with inflation soaring and unemployment rising to 25%.
Millions of Argentinians fell into poverty, and the country’s banking system was paralyzed as the government imposed capital controls and froze bank accounts to prevent capital flight.
In the years that followed, Argentina renegotiated its debt with international creditors, eventually reaching a settlement.
However, the country’s reputation in global financial markets was severely damaged, and Argentina was effectively locked out of international capital markets for many years.
Macro Bonus
Investors who recognized the risks of Argentina’s currency peg and sovereign debt mismanagement were able to avoid significant losses by reducing their exposure to Argentine assets before the crisis hit.
Additionally, those who understood the broader macroeconomic risks – such as the overvalued peso and growing external imbalances – were better positioned to navigate the fallout from the crisis.
The lessons from the Argentine Debt Crisis are still relevant, particularly for emerging markets that rely on currency pegs or have significant levels of foreign-denominated debt.
The Argentine Debt Crisis serves as a reminder of the dangers of currency pegging, sovereign debt mismanagement, and the importance of maintaining flexibility in economic policies.
Market analyses you can’t miss
- Why This Macro Rally Could End in a Disaster
- Trump’s $3 Trillion Trade Shock
- Disaster is arrived